 1800 927 927
 Contact Us
 Find a Broker
In this article:
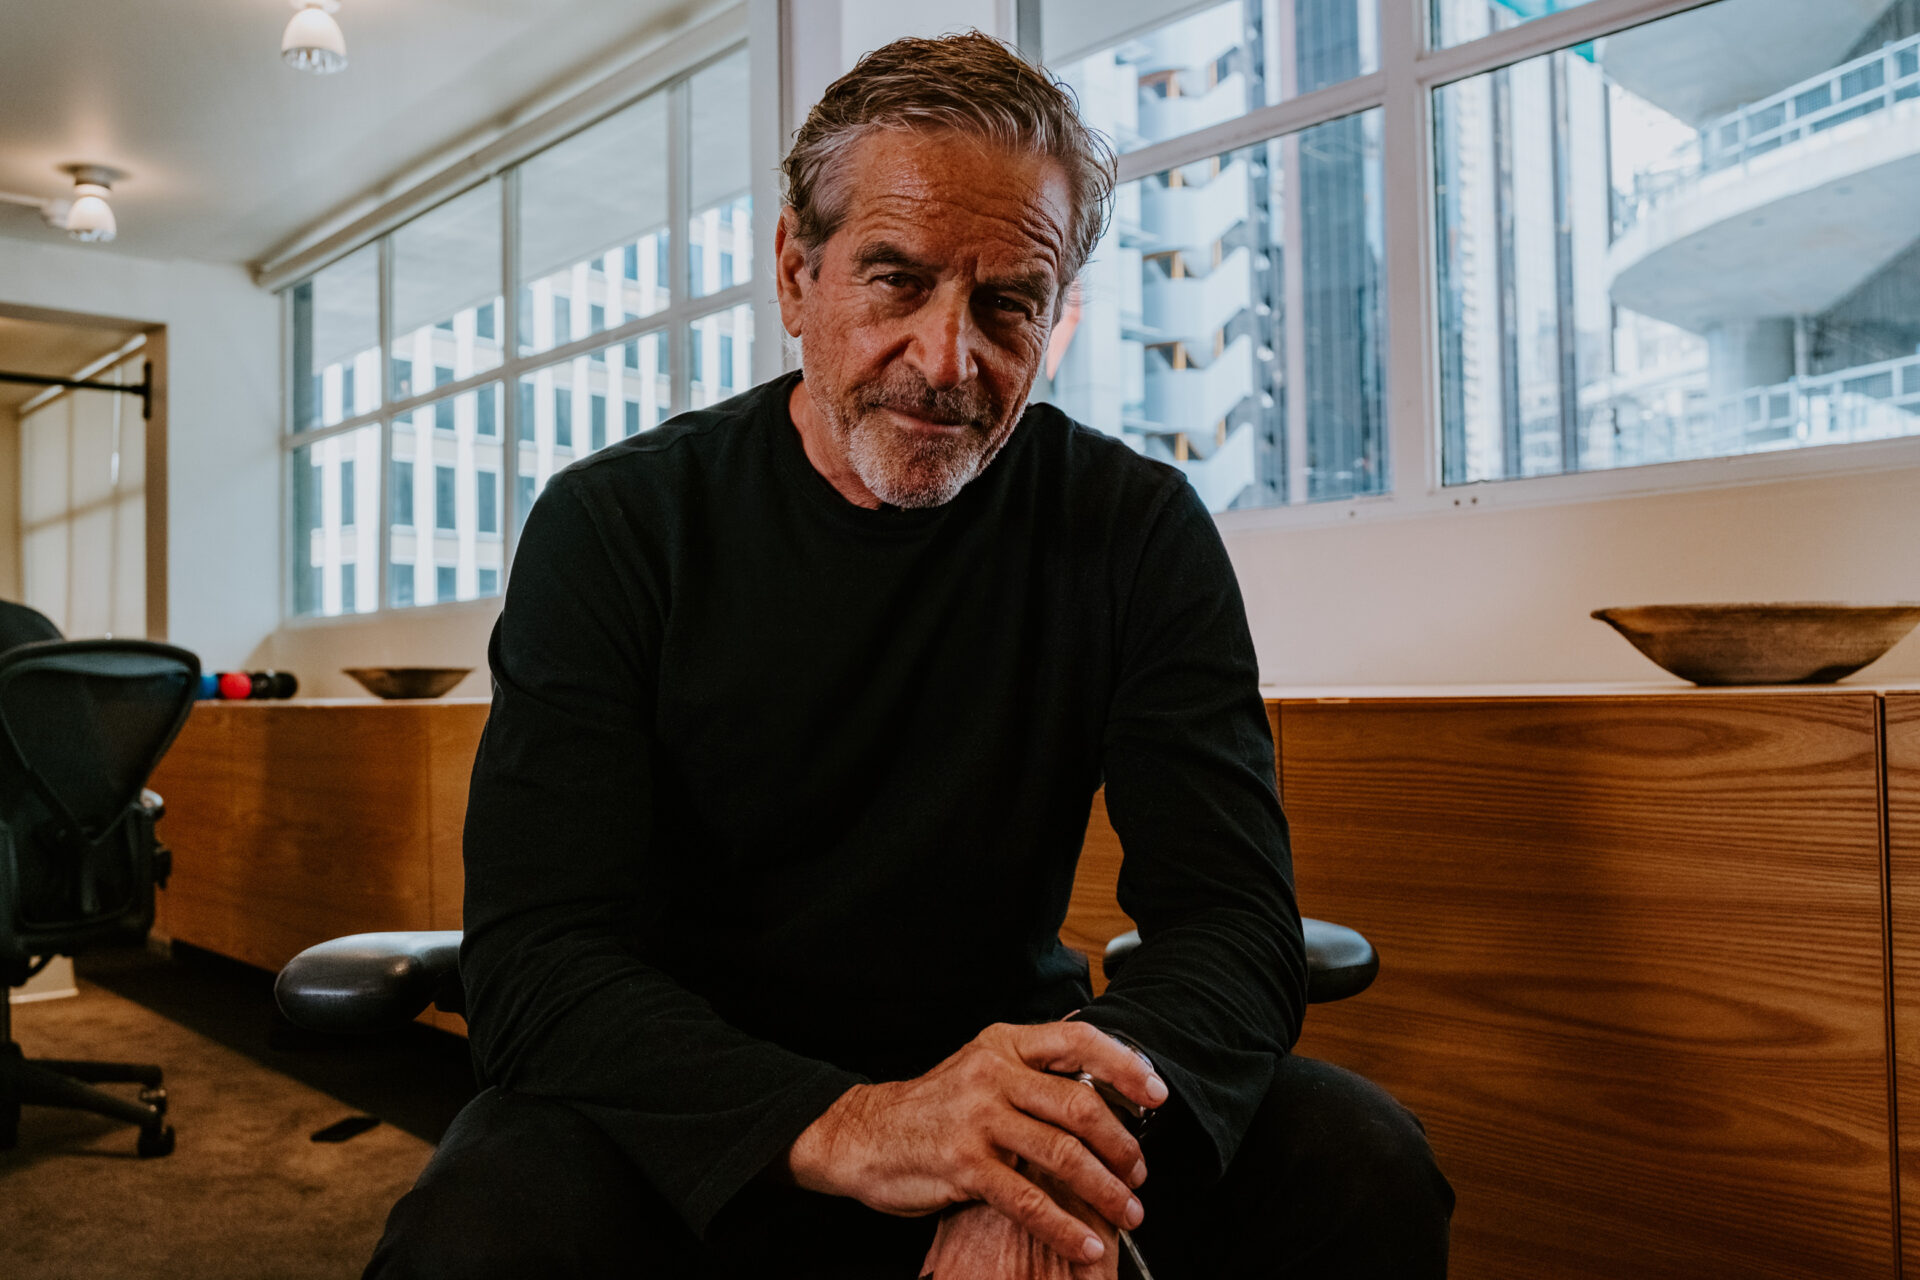
“If the cost of living, and that’s what everybody’s talking about, is going up and is really hurtful to everybody, why the hell are you putting interest rates up, which actually hurts us even more?”
I asked that question in my reaction video immediately after the Reserve Bank lifted the cash rate to 4.60% in September.
Fourth increase this year. Highest it’s been in fifteen years.
I wasn’t reading from a script when I said what I said. I reacted the way I think most of the country reacted: how the hell have we got here and why is it mortgage holders and small businesses copping it in the neck?
My team’s already covered the numbers and broken down the RBA’s statement.
Now for my take. This cuts different. The maths doesn’t add up. At least not in the way it’s being explained to most people.
Why the maths that doesn’t add up
Say your weekly grocery shop has gone up by $100 or $150 a month this year, which for a lot of families sounds about right. That hurts. Nobody’s pretending it doesn’t.
Now compare that to what’s happened to a mortgage. On a $600,000 loan, this single rate rise adds around $91 a month*.
Now apply that to the four hikes this year. That’s $364 a month, or $4,368 a year, gone before you’ve bought a single thing.
On a million-dollar loan it’s around $608 a month, roughly $7,296 a year. This assumes the banks pass the rise in full, which is exactly what’s happening every time so far.
And the money you put into your mortgage is after tax dollars. For every extra $100 in repayments, you’ll need to earn $150.
So, the grocery bill goes up by a hundred or so, and everyone agrees that’s a genuine cost of living problem.
The mortgage goes up by three, four, sometimes seven times that, because of a decision aimed at solving the exact same cost of living problem, and somehow that’s just supposed to be accepted as the medicine working.
I don’t think you need an economics degree to see something is off with that logic. There seems to be something terribly unfair about it, and I said so on camera because I think somebody needs to.
Stagflation isn’t just a textbook word anymore
“At the same time high inflation is what they call stagflation. Stagflation is a major issue, one we haven’t really experienced since the late seventies, and that is a real concern.”
In plain terms, stagflation is prices staying high while growth slows down at the same time. It’s the one combination the Reserve Bank has no clean tool for because the usual fix for inflation is to slow the economy down further, which is precisely what’s already starting to happen.
CBA’s own Household Spending Insights data for August, released in September, shows spending growth slowing to just 0.1% for the month, down from 0.6% in July, with annual growth down to 4.7% from 5.2%.
That’s not a forecast. That’s households already pulling back in real time. When people stop spending because they’re worried about their mortgage, that’s not the economy healing. That’s the economy stalling while prices keep climbing regardless.
It’s not just mortgage holders. Small business is copping it too.
Most of the coverage this week has focused on mortgage holders. Fair enough. That’s where the pain’s most visible. But I’ve spent my career backing self-employed Australians and small business owners, and this decision lands on them just as hard, arguably harder.
NAB’s Monthly Business Survey for August shows business conditions turning negative for the first time in six years, down 5 points, with profitability down 10 points and confidence down another 2 points. Cost pressures are still elevated.
That’s before this latest hike properly filters through business loans and overdrafts, most of which move with the cash rate the same way a variable mortgage does.
Think about what that actually means for someone running a small business.
Their borrowing costs go up, the same as a mortgage holder. Their own costs, stock, wages, insurance, energy, keep climbing. And their customers, the households I’ve just described pulling back on spending, are buying less from them at exactly the same time.
It’s a squeeze from every direction and it barely gets a mention when the conversation is all about mortgage repayments.
Who’s actually representing us?
“The system is patently unfair. They need to spread that pain across the whole country instead of just getting the people who have debt pay for it. The engine room is copping it in the neck, and its mortgage holders are copping it in the neck. Middle Australia, basically. So I don’t know who’s representing us.”
To be fair to the Reserve Bank, and I try to be, because it’s an easy target and not always the right one, this isn’t really their fault in the way people want to make it their fault.
“It’s not the Reserve Bank’s fault, this is all written down in their mandate.”
Their job is to bring inflation back to target using the one lever they’ve got. The cash rate, and borrowers with a mortgage are simply the group that lever pulls hardest on. It’s just how the tool works.
It means the cost is being carried almost entirely by one group, while everyone else who’s contributed to inflation, global oil markets, an energy shock nobody here voted for, AI driven demand pushing up the price of everything from chips to electricity, gets to watch from the sidelines.
It’s also worth asking whether hammering borrowers alone is even working. Market commentary this month has pointed to a possible peak to trough decline of around 13% in capital city home values if the current run of hikes plays out, shaving somewhere between 0.4 and 1 percent off GDP over time.
That’s not a side effect anyone’s celebrating, and it’s exactly the kind of thing that deserves an honest public conversation instead of a press release full of careful language.
What I’d tell you if you were sitting across from me
I’m not going to give you a lecture with ten steps. If you’re a mortgage holder or a business owner trying to figure out what to actually do this week, here’s what I’d say to your face.
Know your actual rate, not just your repayment. Most people can tell you what they pay each month. Far fewer can tell you the interest rate they’re paying, and that’s the number that matters when you’re working out whether you’re being looked after.
If it’s been more than twelve months since you checked, assume you’re not getting a good deal anymore. The cash rate has moved four times this year alone. Whatever you were offered a year ago isn’t necessarily what’s available to you now, in either direction.
Talk to someone before you assume there’s nothing you can do. Whether it’s your home loan or your business finance, a broker who actually compares lenders, rather than one who works for a single bank, can tell you in ten minutes whether you’re better off than you think, or worse.
“Be great though if someone could call this stuff out at some stage or other, and I’m doing it right now. Probably gonna get in trouble for doing it, but good luck.”
Probably will. But somebody had to say the quiet part out loud, and I’d rather it came from someone who’s spent his whole career on the side of borrowers than not get said at all.
If you want to know exactly where your own loan or business finance stands right now, that’s what my brokers are for. Start with your home loan at ybr.com.au/cut, or your business finance at ybr.com.au/business-loans.
Source: Canstar. Based on an owner-occupier making principal and interest repayments with 25 years remaining on their loan term in February 2026, realising the average variable rate as per the RBA. This article is general and does not take into account your objectives, financial situation or needs.
