 1800 927 927
 Contact Us
 Find a Broker
Self-Employed Home Loans, Built Around Your Business
You back yourself every day. Your lender should too. Self-employed income looks different on paper, but that shouldn’t mean fewer options. Our brokers compare 50+ lenders to find one that gets how you earn.
- \50+ lenders compared
- \Low doc & alt doc specialists
- \Local broker Australia-wide
Self-Employed - Leads Contact Form
Start your journey, speak with a home loan expert today!
LOAN OPTIONS
Full doc, low doc and alt doc
MADE FOR
Sole traders, contractors, company and trust owners
LENDERS COMPARED
50+ banks and non-bank lenders
NEWER BUSINESS?
Some lenders accept 6-12 months of trading
YOUR OPTIONS
Find the right self-employed home loan
Every self-employed borrower is different. Choose the option that matches your paperwork, and we’ll match you with lenders who get it.
Full doc home loans
Two years of tax returns and financials ready? You could access the same rates as PAYG borrowers.
Low doc home loans
Tax returns not lodged or paperwork behind? Use BAS, bank statements or an accountant’s declaration.
Alt doc home loans
Business growing faster than your tax returns show? Verify your income with recent trading.
Bridging loans
Buying your next home before you sell? We bridge the gap for self-employed buyers too.
THE BASICS
What is a self-employed home loan?
QUICK ANSWER
A self-employed home loan is a home loan assessed on your business income rather than a payslip. Most lenders ask for two years of tax returns and notices of assessment, while low doc and alt doc options accept other evidence. The right lender depends on how your income is structured.
What lenders look at
- EHow long you've held your ABN
- EYour taxable income over the last two years, and whether it's rising
- EYour business structure: sole trader, partnership, company or trust
- EAdd-backs such as depreciation and one-off expenses
- EYour credit history, deposit and existing debts
How much can I borrow if I’m self-employed?
Your borrowing power depends on your verified income, expenses, existing debts and deposit. Lenders treat business income differently, so the same numbers can give a different result from one lender to the next.
A quick estimate helps before you talk to a broker.
PAPERWORK
Documents you’ll need, by business type
For a full doc loan. If these aren’t ready, a low doc or alt doc loan may suit you better.
Sole trader or partnership
-
Two years of personal tax returns
-
Notices of assessment
-
ABN registration
-
Recent business bank statements
Company
-
Two years of company and personal tax returns
-
Company financial statements
-
Notices of assessment
-
ABN and ACN details
Trust
-
Two years of trust and personal tax returns
-
Trust financial statements
-
Trust deed
-
Evidence of distributions
Tax returns not ready?
Low doc and alt doc home loans let you prove your income with BAS, bank statements or an accountant’s declaration.
MORE THAN A CALCULATOR
Your business.
Your income.
Your fingerprint.
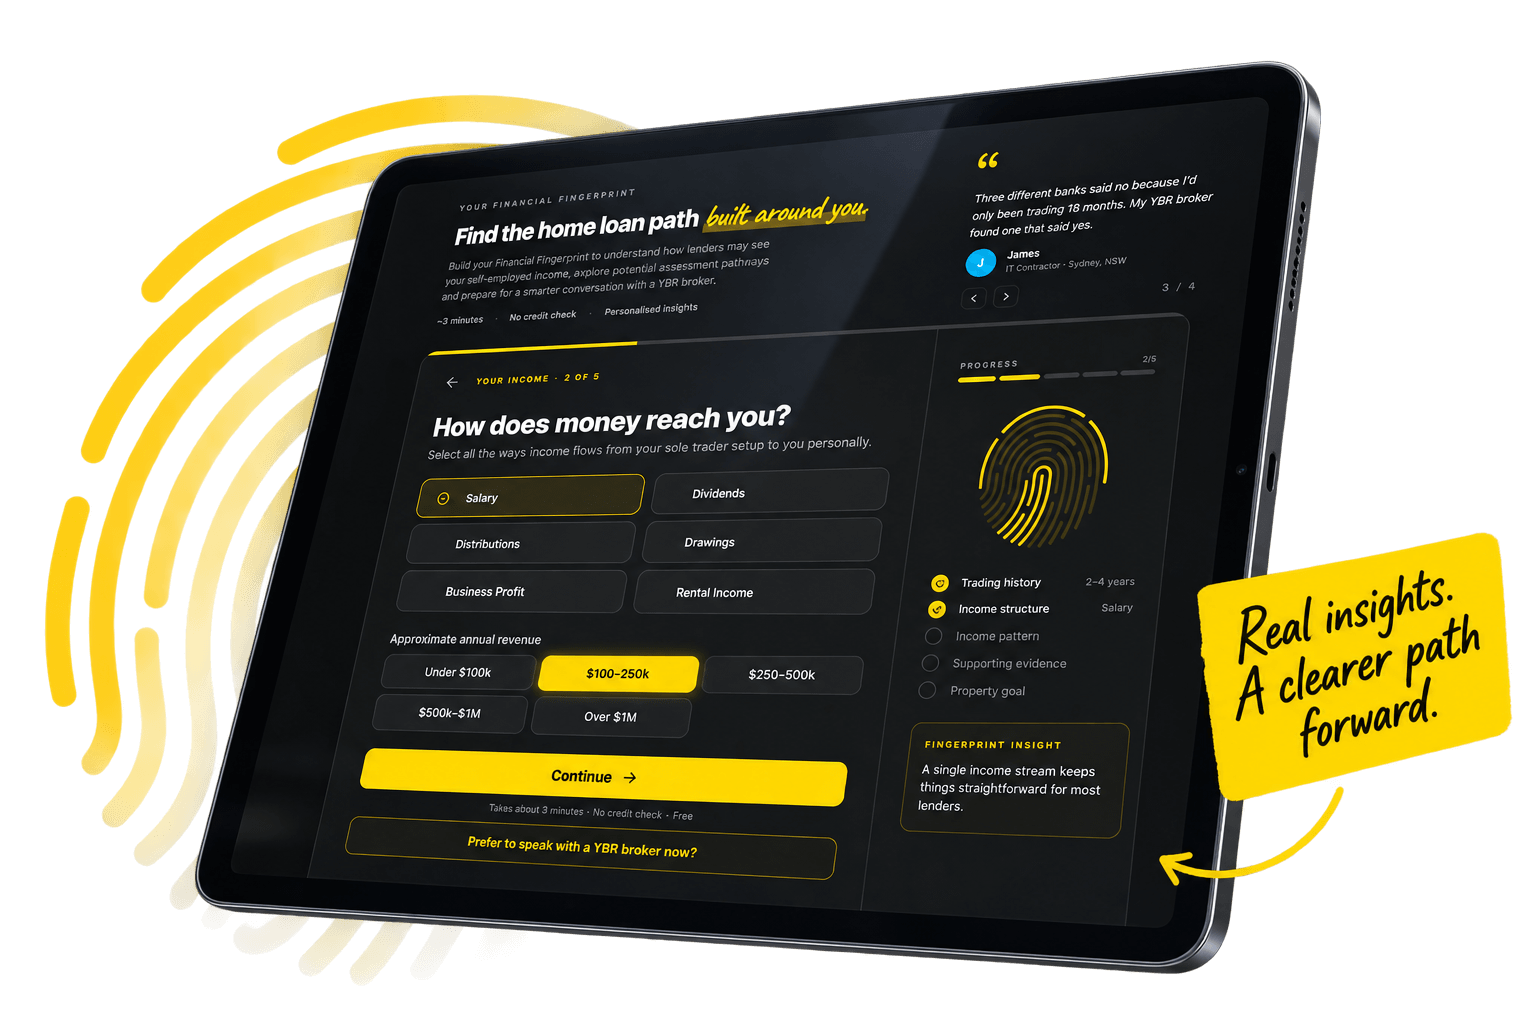
Build your Financial Fingerprint and discover how your self-employed income, business structure, financial history and supporting evidence may be viewed differently by different lenders.
See what’s shaping your profile, explore potential assessment pathways and discover what could change your options, before you even speak with a broker.
WHY YELLOW BRICK ROAD
Why go with us?
01
We search, compare & negotiate
We research the market and compare rates from our panel of 50+ lenders to find a loan that suits your needs.
02
We do the heavy lifting
We keep the application process simple, managing the paperwork from application right through to settlement.
03
You choose the right loan
We present the options and the facts, so you can pick the home loan that fits your goals.
CALCULATORS
See how much you could save
What I can borrow?
Repayments calculator
Stamp duty calculator
Extra repayments
CLIENT STORIES
What our clients have to say

Excellent service and attention to detail. We would highly recommend YBR and are extremely grateful for the support we receive from Struan and Jess.
Dale Wylie
Self-Employed

I’ve dealt with Andrew and his team at Yellow Brick Road Rosanna on many occasions and he is excellent to work with. Very professional. A top result for our home loan.
Matt Hodgson
Self-Employed

Andrew has given us great service every time we have used Yellow Brick Road at Northlakes to refinance our home loans. Andrew is very approachable, honest and knowledgable.
Melissa Luhrman
Self-employed
FAQS
Self-employed home loan FAQs
Can I get a home loan if I've been self-employed for less than two years?
Yes, some lenders will consider you with 12 months of trading, or less if you’ve stayed in the same industry. You may need a larger deposit or a low doc or alt doc loan. A broker can tell you which lenders suit your timeline.
What's the difference between full doc, low doc and alt doc?
Full doc uses two years of tax returns and financials, like a standard home loan. Low doc relies mainly on an accountant’s declaration. Alt doc uses recent BAS and bank statements. Full doc usually has the lowest rates.
Will I pay a higher interest rate because I'm self-employed?
Not if you can provide full financials. Self-employed borrowers with up-to-date tax returns can often access the same rates as PAYG borrowers. Low doc and alt doc loans are usually priced a little higher.
Do I need an accountant to apply?
It helps. Most lenders want tax returns and financials prepared by an accountant, and low doc and alt doc loans usually need a signed accountant’s declaration of your income.
How do lenders treat add-backs like depreciation?
Many lenders add back non-cash expenses such as depreciation and some one-off costs to your taxable income. This can increase your borrowing power, and policies differ by lender.
Can I use my business income to buy an investment property?
Yes. The same income rules apply. Your broker will look at your total income, existing debts and the rental income from the property.
GUIDES AND TOOLS
Learn more before you talk to a broker

How to Be Self Employed & Get an Affordable Home Loan
You’re self-employed but does that mean you won’t get a good home loan deal?

A Guide to Home loans for the Self-Employed
Here are some potential challenges self-employed professionals face while applying for home loans along with effective tips to overcome them.

Borrowing when self employed
Getting a loan approved when you’re self-employed can be tricky. Having a strategy and understanding your business structure will be a a major advantage. Here are some other tips to help.
Your business doesn’t fit a standard mould.
Your home loan doesn’t have to either.
We’re here to help
Self-Employed - Leads Contact Form
Start your journey, speak with a home loan expert today!